$792K ground-up build in Dallas, TX — 80% LTC, 12-day close
Illustrative case study modelled on typical files for this program; figures are examples, not a funded loan.
- Land
- $254,000
- Construction budget
- $736,000
- As-complete value
- $1,534,000
- Loan
- $792,000
- Loan-to-cost
- 80%
- Rate
- 9.25%
- Points
- 2
- Experience tier
- Tier 2 · Builder
- Term
- 24 months, interest-only
- Days to close
- 12
- Units
- Single-family
- Exit
- DSCR refinance
Situation
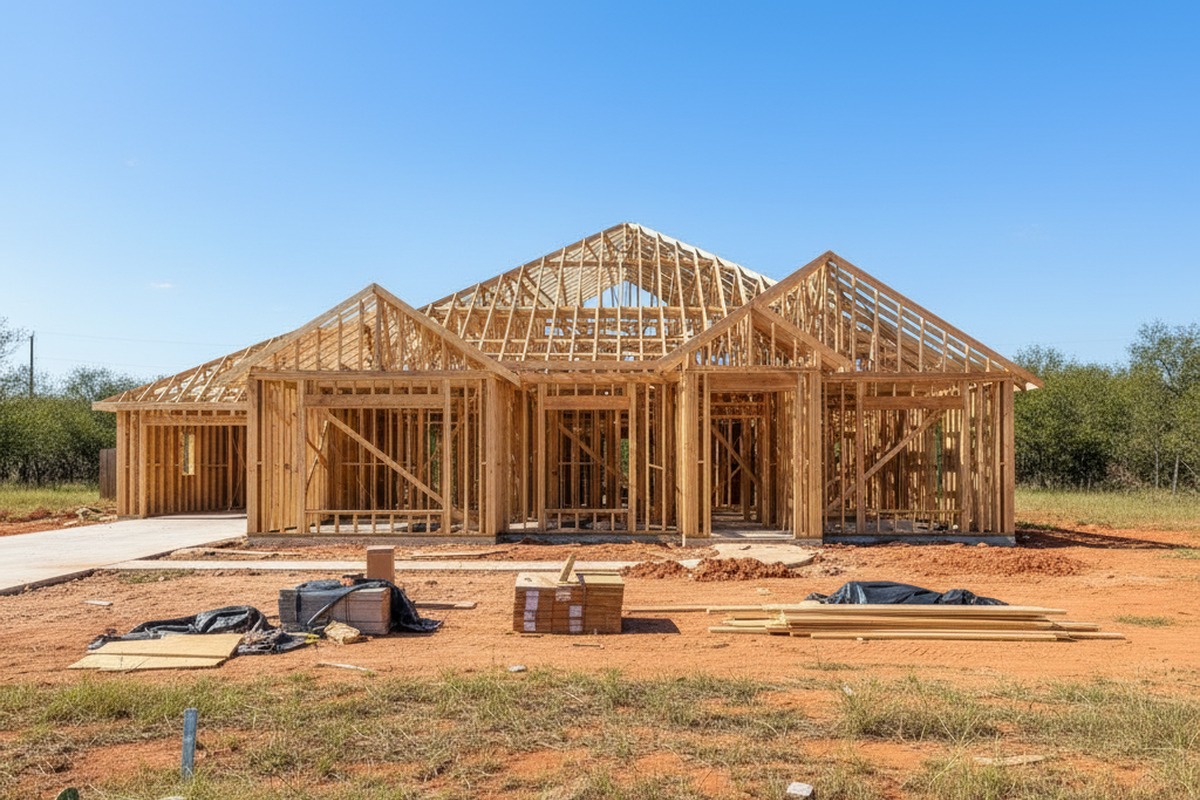
This illustrative Dallas, TX scenario models a single-family build to rent with four completed projects. The plan covers a documented single-family plan, foundation, framing, mechanicals and finishes. The budget separates each phase before closing; city-level location is illustrative and identifies no real property or borrower.
Structure
Tier 2 sizes the example at 80% of total cost, subject to the tier’s purchase-and-rehab or construction-cost limit and value cap. The selected tier sets interest-only pricing and points. A complete contract, scope, entity file and GC record model a 12-day close; final terms remain subject to underwriting.
In numbers: a $792,000 loan against $990,000 of total cost left $198,000 of borrower equity in the deal. The value test — 75% of the $1,534,000 as-complete value ($1,150,500) — sat above the loan, so cost, not value, set the size. Fully drawn, interest-only carry at 9.25% works out to about $6,105 a month, and 2 points of origination came to $15,840 at closing.
Draws
Foundation, framing, rough-in and final phases each have an allocated budget. Photos, invoices and an inspection appropriate to the completed milestone support each request; undisbursed funds remain tied to the approved scope.
The file
What was in the file: the land documents, the plans and specifications, the itemised hard- and soft-cost budget and build schedule, the as-complete value estimate with comparable new-construction sales, the GC agreement with license and insurance, builder’s risk insurance, and bank statements showing the cash to close and six months of reserves. A rent survey supported the planned refinance, so the construction loan and the exit were sized as one plan. The appraisal valued the home as complete against recent new-construction sales nearby. Every checklist item came back inside 48 hours, which kept the close at the fast end of the range. Title was opened on the day of application and insurance was bound before the appraisal came back. The term sheet set the final leverage and pricing against the published maximums.
Exit
The model ends with a leased single-family home and a same-desk DSCR refinance. Rent, value and the long-term loan’s own qualification determine the exit; no refinance approval or future value is assumed.
- Named tier matches leverage and pricing
- Single-family scope and itemised budget
- GC record reviewed with the file
- Exit evaluated independently
- Week 1.7Close
- Week 6Draw 1
- Week 12Draw 2
- Week 20Draw 3
- Week 30Draw 4
- Week 40DSCR refinance