$510K fix & flip in Sacramento, CA — 85% LTC, 14-day close
Illustrative case study modelled on typical files for this program; figures are examples, not a funded loan.
- Purchase
- $415,000
- Renovation budget
- $185,000
- After-repair value
- $790,000
- Loan
- $510,000
- Loan-to-cost
- 85%
- Rate
- 9.00%
- Points
- 2
- Term
- 12 months, interest-only
- Days to close
- 14
- Units
- Single-family
- Exit
- Sale
Situation
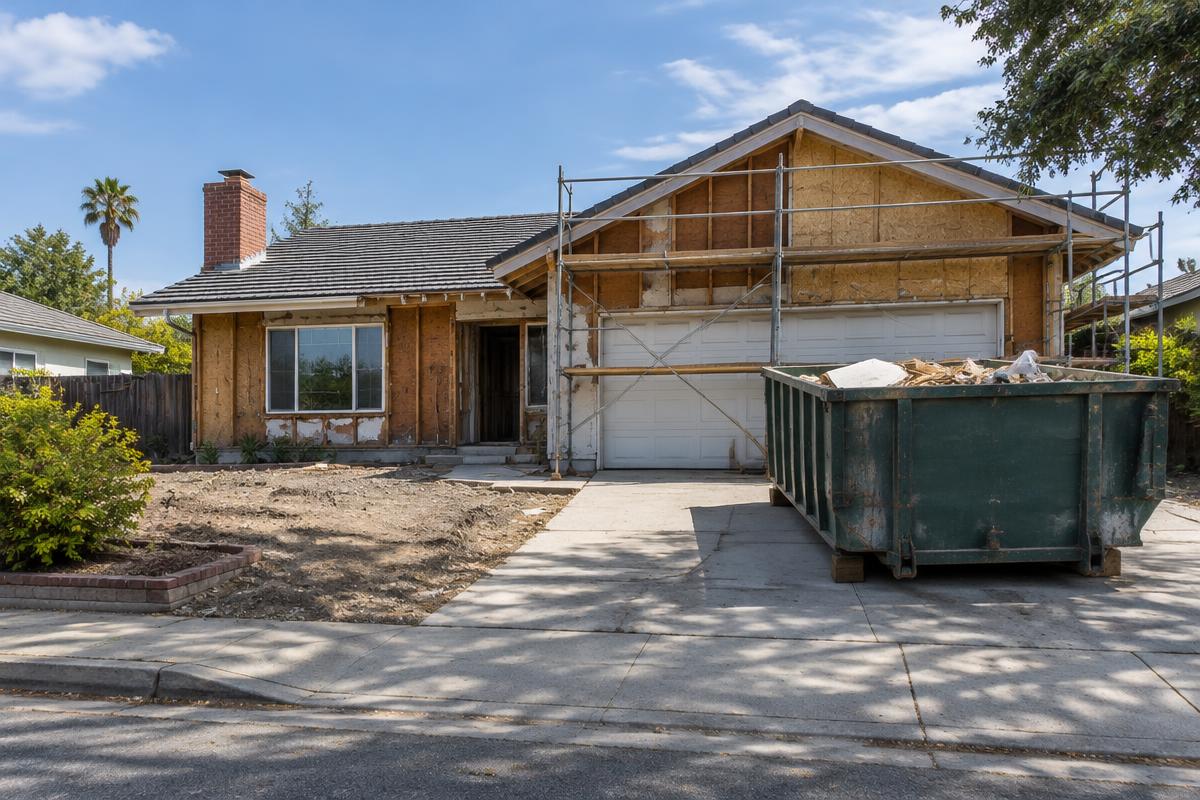
A repeat flipper bought a dated single-family house in an established Sacramento neighbourhood where renovated homes command a strong premium. The scope was a full interior gut: kitchen, baths, systems and finishes.
Structure
The loan funded 85% of the $600,000 total cost at 9.00% with two points on a 12-month interest-only term, inside the 75% cap on the $790,000 after-repair value. Permitted plans and the GC’s itemised bid were in at application; the file closed in 14 days.
In numbers: a $510,000 loan against $600,000 of total cost left $90,000 of borrower equity in the deal. The value test — 75% of the $790,000 after-repair value ($592,500) — sat above the loan, so cost, not value, set the size. Fully drawn, interest-only carry at 9.00% works out to about $3,825 a month, and 2 points of origination came to $10,200 at closing.
Draws
Four milestone draws — demolition, mechanicals, kitchen and baths, finishes — were released against photos and invoices with remote review where the work allowed it.
The file
What was in the file: the purchase contract, the itemised scope of work and renovation budget, the after-repair value estimate with comparable sales, the GC agreement with license and insurance, two months of bank statements showing the cash to close and six months of reserves, and the LLC documents and ID. The appraisal valued the house as renovated against recent comparable sales nearby. Every checklist item came back inside 48 hours, which kept the close at the fast end of the range. Title was opened on the day of application and insurance was bound before the appraisal came back. The term sheet set the final leverage and pricing against the published maximums.
Exit
The finished home sold to an owner-occupant buyer, repaying the loan inside the original term.
- Permits and bid ready at application
- Renovated comparables supported the ARV
- Milestone draws matched the crew’s schedule
- Strong resale market