$425K fix & flip in Philadelphia, PA — 85% LTC, 13-day close
Illustrative case study modelled on typical files for this program; figures are examples, not a funded loan.
- Purchase
- $310,000
- Renovation budget
- $190,000
- After-repair value
- $690,000
- Loan
- $425,000
- Loan-to-cost
- 85%
- Rate
- 9.00%
- Points
- 2
- Term
- 18 months, interest-only
- Days to close
- 13
- Units
- 1 → 2 units
- Exit
- DSCR refinance
Situation
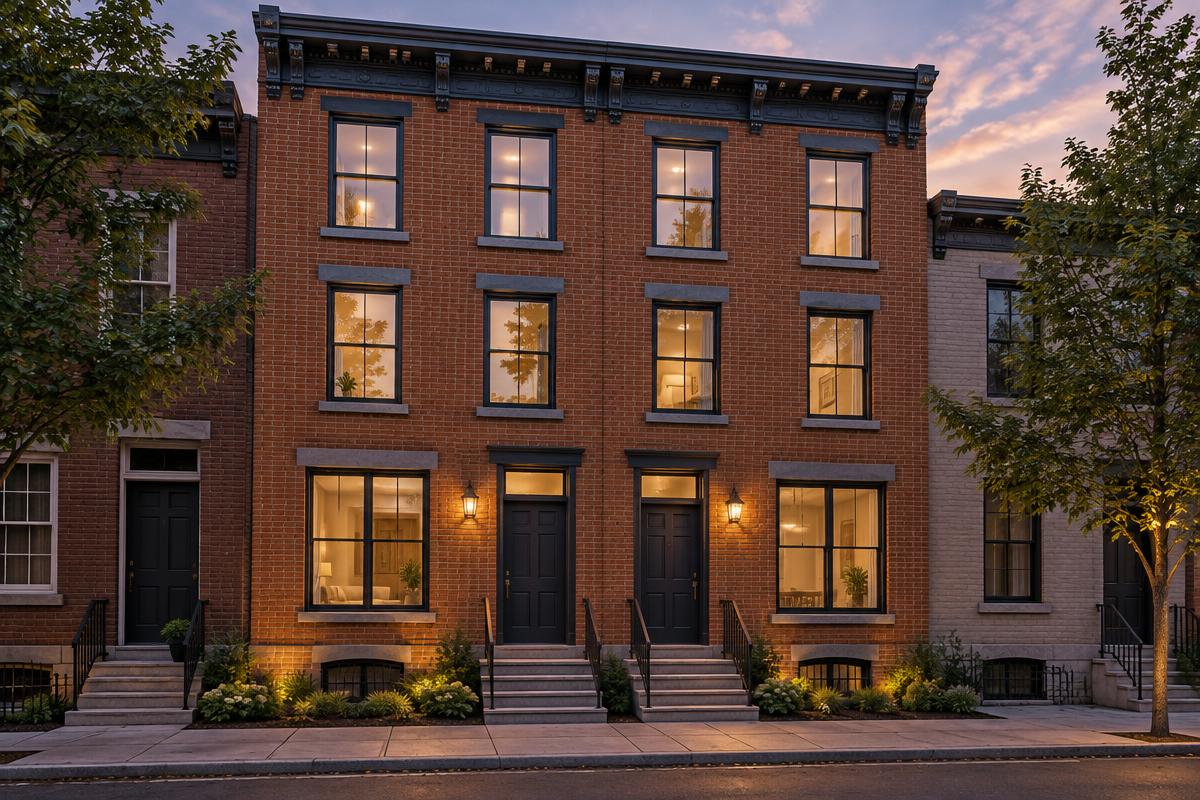
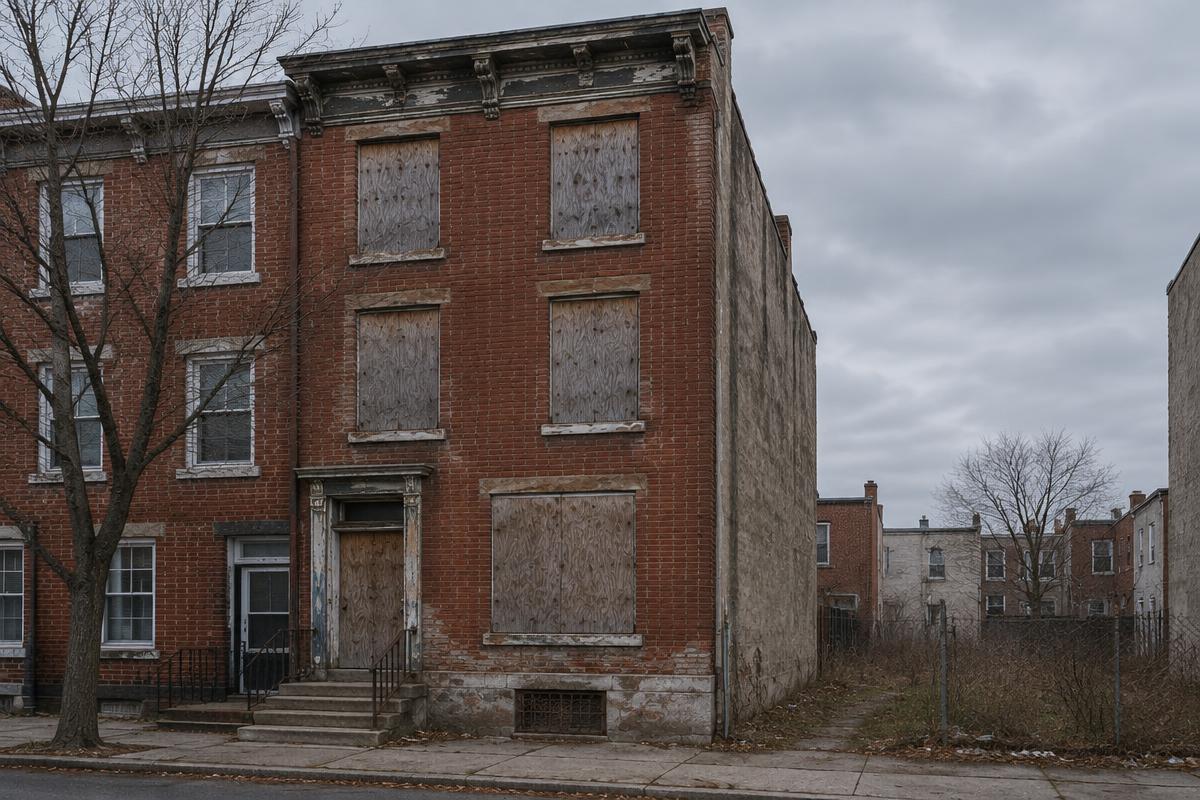
An investor with several completed rehabs bought a large rowhouse that zoning allowed to be converted into two units. Two rents on one deed would be worth more than one large house, but the conversion needed separate utilities, egress and a permitted plan.
Structure
The loan funded 85% of the $500,000 cost on an 18-month interest-only term, with an extension available if permitting ran long. The as-converted value of $690,000 kept the loan comfortably below the 75% ARV ceiling. Rate 9.00% and two points; the file closed in 13 days.
In numbers: a $425,000 loan against $500,000 of total cost left $75,000 of borrower equity in the deal. The value test — 75% of the $690,000 after-repair value ($517,500) — sat above the loan, so cost, not value, set the size. Fully drawn, interest-only carry at 9.00% works out to about $3,188 a month, and 2 points of origination came to $8,500 at closing.
Draws
Draws followed the permitted plan: structural and framing, separate electrical and plumbing services, fire separation and egress, then two kitchens and finishes. Photos and invoices supported each release.
The file
What was in the file at application: the purchase contract, a zoning confirmation for two units, the architect’s conversion plan, the GC’s itemised bid broken out by unit, and evidence of the investor’s previous completed rehabs. Bank statements covered the cash to close and six months of reserves. Because the conversion added a unit, the appraisal was ordered on an as-converted basis so the value test reflected two rents rather than one house.
Exit
With both units leased, the investor refinanced into a DSCR loan qualified on the combined rent. No prepayment penalty meant the bridge could be retired the moment the units stabilised.
- Zoning confirmed before closing
- Term long enough for permits
- Two leases supported the DSCR refinance
- No prepayment penalty on early payoff