$234K fix & flip in Louisville, KY — 85% LTC, 13-day close
Illustrative case study modelled on typical files for this program; figures are examples, not a funded loan.
- Purchase
- $185,000
- Renovation budget
- $90,000
- After-repair value
- $360,000
- Loan
- $233,750
- Loan-to-cost
- 85%
- Rate
- 9.00%
- Points
- 2
- Term
- 12 months, interest-only
- Days to close
- 13
- Units
- Single-family
- Exit
- DSCR refinance
Situation
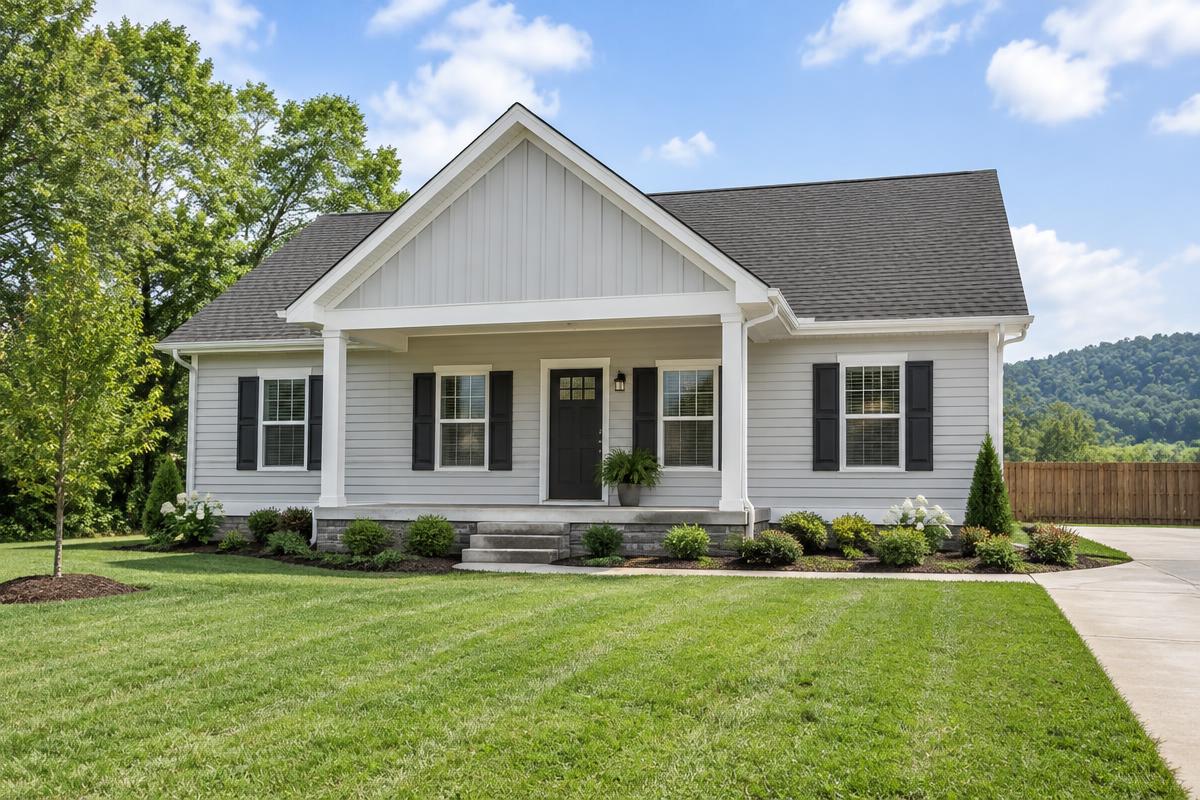
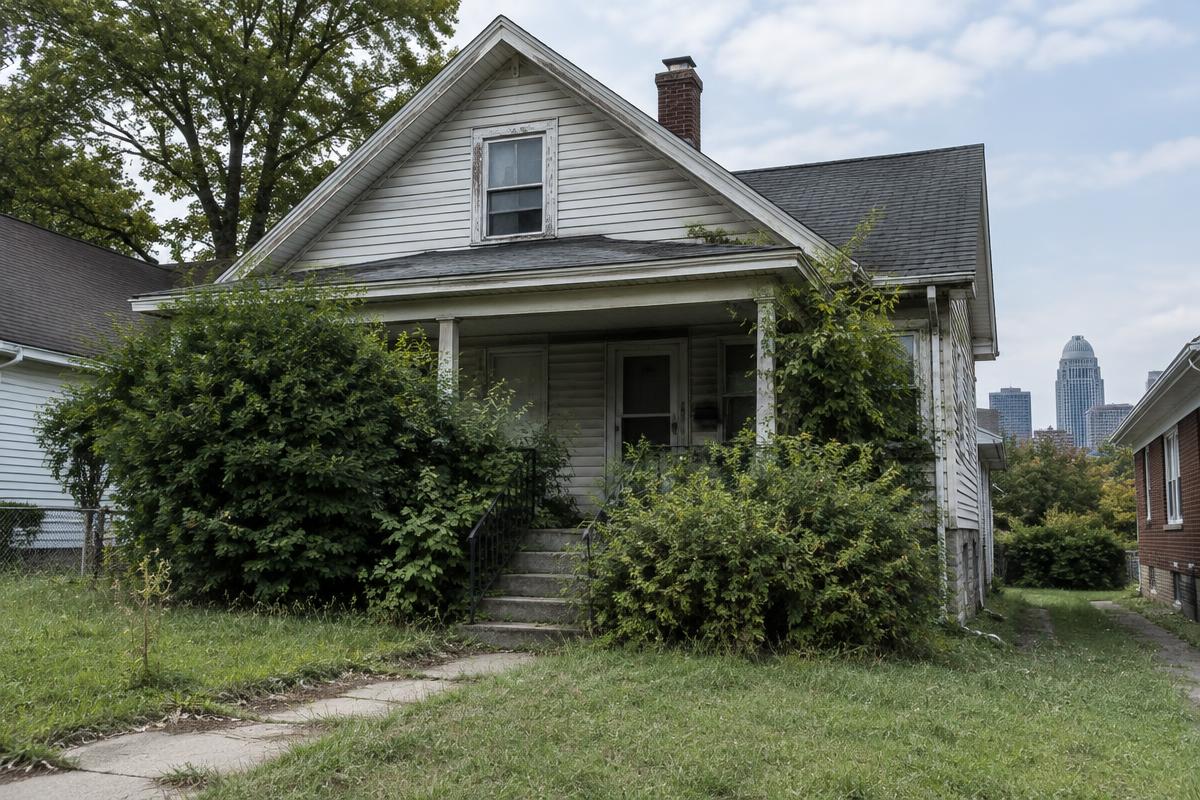
A portfolio investor bought a dated single-family house in a Louisville neighbourhood with reliable rents, planning to renovate, lease and hold.
Structure
The loan funded 85% of the $275,000 cost at 9.00% with two points, inside the 75% cap on the $360,000 after-repair value. Contract, scope and entity documents were in at application; the close took 13 days.
In numbers: a $233,750 loan against $275,000 of total cost left $41,250 of borrower equity in the deal. The value test — 75% of the $360,000 after-repair value ($270,000) — sat above the loan, so cost, not value, set the size. Fully drawn, interest-only carry at 9.00% works out to about $1,753 a month, and 2 points of origination came to $4,675 at closing.
Draws
Three draws — systems, kitchen and baths, finishes — were reviewed remotely against the approved budget.
The file
What was in the file: the purchase contract, the itemised scope of work and renovation budget, the after-repair value estimate with comparable sales, the GC agreement with license and insurance, two months of bank statements showing the cash to close and six months of reserves, and the LLC documents and ID. A rent survey supported the planned refinance, so the construction loan and the exit were sized as one plan. The appraisal valued the house as renovated against recent comparable sales nearby. Every checklist item came back inside 48 hours, which kept the close at the fast end of the range. Title was opened on the day of application and insurance was bound before the appraisal came back. The term sheet set the final leverage and pricing against the published maximums.
Exit
Once leased, the house refinanced into a DSCR rental loan with the same desk, and the short-term loan paid off with no prepayment penalty.
- Hold plan from day one
- Rent comparables in the file
- Same-desk refinance
- Remote draws kept the schedule