$200K fix & flip in Indianapolis, IN — 85% LTC, 10-day close
Illustrative case study modelled on typical files for this program; figures are examples, not a funded loan.
- Purchase
- $150,000
- Renovation budget
- $85,000
- After-repair value
- $310,000
- Loan
- $199,750
- Loan-to-cost
- 85%
- Rate
- 9.00%
- Points
- 2
- Term
- 12 months, interest-only
- Days to close
- 10
- Units
- Single-family
- Exit
- Sale
Situation
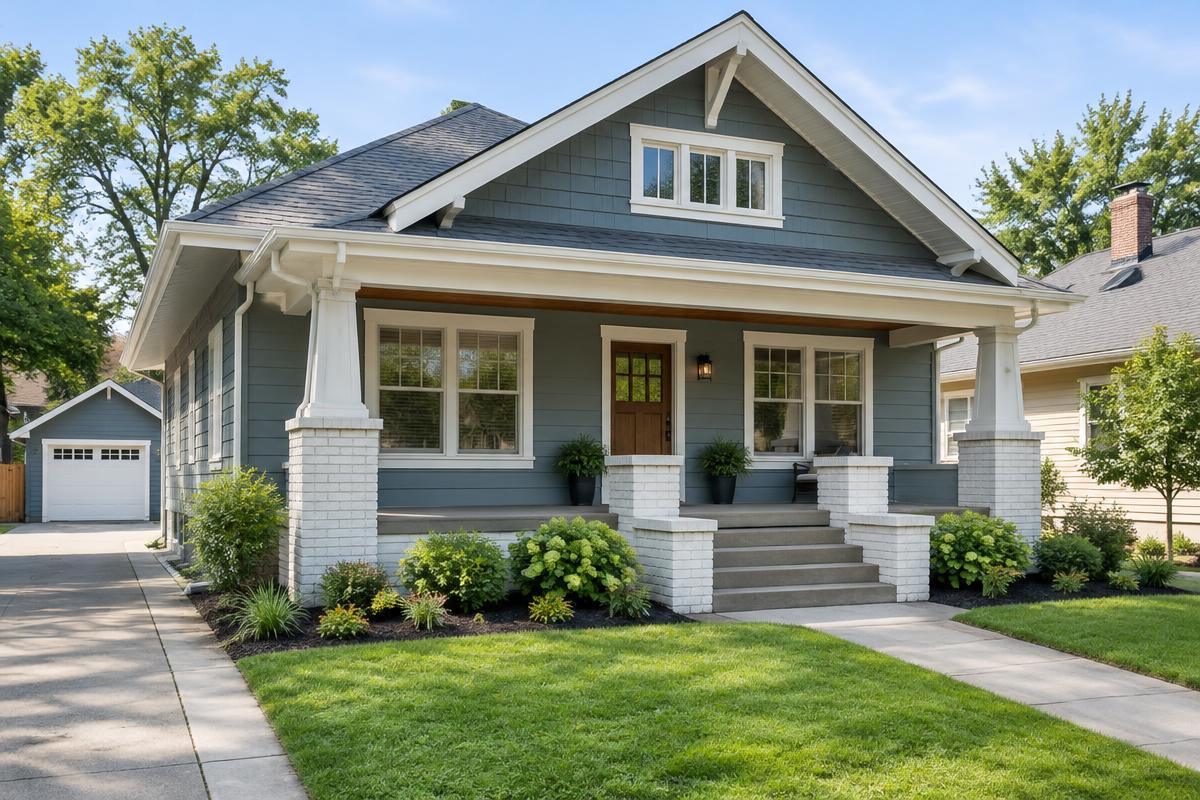
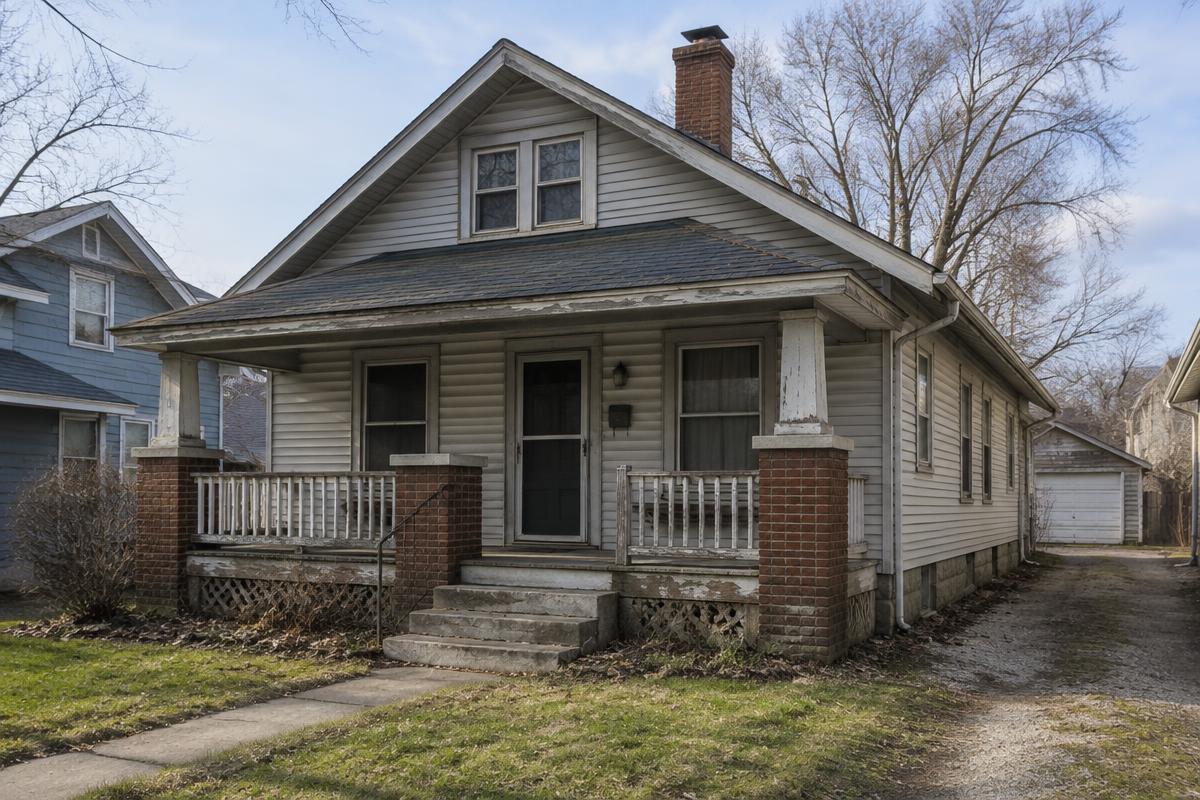
A flipper with more than ten completed projects bought a solid Indianapolis bungalow below renovated comparables, with a predictable scope of systems, kitchen, baths and finishes.
Structure
A Tier 3 repeat file: the experience review was a formality. The loan funded 85% of the $235,000 cost at 9.00% with two points and closed in 10 days — the fast end of the range.
In numbers: a $199,750 loan against $235,000 of total cost left $35,250 of borrower equity in the deal. The value test — 75% of the $310,000 after-repair value ($232,500) — sat above the loan, so cost, not value, set the size. Fully drawn, interest-only carry at 9.00% works out to about $1,498 a month, and 2 points of origination came to $3,995 at closing.
Draws
Three milestone draws were released against photos and invoices from the investor’s regular crew.
The file
What was in the file: the purchase contract, the itemised scope of work and renovation budget, the after-repair value estimate with comparable sales, the GC agreement with license and insurance, two months of bank statements showing the cash to close and six months of reserves, and the LLC documents and ID. The appraisal valued the house as renovated against recent comparable sales nearby. Every checklist item came back inside 48 hours, which kept the close at the fast end of the range. Title was opened on the day of application and insurance was bound before the appraisal came back. The term sheet set the final leverage and pricing against the published maximums.
Exit
The house sold to a first-time buyer, and the investor brought the next project to the same desk.
- Repeat-builder track record
- Ten-day close on a complete file
- Line-item pricing from prior houses
- Entry price point with deep demand